Key takeaways
- Regulators and international standard setters like the FATF have promoted a risk-based approach to AML for nearly ten years, yet many programs remain focused on check-box compliance.
- Rule-based transaction monitoring has an estimated 95% false positive rate according to industry research, while also missing suspicious behavior that does not align with a predefined typology.
- AI transaction monitoring solutions can reduce false positives by up to 95% while detecting more anomalous behavior and previously unidentified typologies.
- Upon discovering a new financial crime typology, it can take 6-12 months to reprogram legacy rule-based systems to detect it.
- Travelex Bank reported a 10x reduction in false positives after implementing ThetaRay, with a proof of concept completed in only 3 days and full integration in only 2 months.
Introduction: how is AI changing financial crime compliance?
In the ever-evolving landscape of financial crime, traditional rule-based transaction monitoring is under challenge. As financial institutions grapple with the necessity to remain both compliant and agile, there is a clear need for a paradigm shift.
The trends are showing a tectonic shift from static, one-size-fits-all rules to the adaptive and flexible terrain of a risk-based approach. Regulators and international standard setters like the Financial Action Task Force (FATF) have promoted a risk-based approach for nearly ten years. Yet in practice, many programs remain focused on check-box compliance rather than ensuring a genuine understanding of threats and a targeted, risk-driven approach.
The ability to make this change has been transformed by powerful new technologies in the form of AI. Compliance is no longer confined to rule sets. Instead, it draws on the intelligence, precision and dynamic adaptability of risk-based systems to achieve better results in identifying and preventing money laundering, terrorist financing and other criminal activity.
This white paper examines the ways AI-powered transaction monitoring is helping financial institutions of every scale shift to a risk-based approach. We examine the implications, benefits and transformative potential of utilizing AI technology to foster efficiency and effectiveness, ensuring a secure and robust financial crime compliance (FCC) program.
Shifting paradigms in transaction monitoring: embracing a risk-based approach
What are the two major problems with rule-based transaction monitoring?
- Vast amounts of suspicious behavior go undetected because they do not align with a predefined typology.
- What is detected is not actually suspicious at all (an estimated 95% false positive rate, according to industry research).
Rule-based systems skew heavily towards false positives (needless alerts on unsuspicious activity, which pose a significant resource strain) and false negatives (actual risks going undetected).
AI solutions generate highly accurate results, enhancing both efficiency and effectiveness. They dramatically reduce the number of false positives, by up to 95%, creating a smaller volume of alerts for analysts to investigate.
| Result | Outcome | What it means |
|---|---|---|
| True positive | Good outcome | Alert for suspicious activity |
| False positive | Bad outcome | Alert for non-suspicious activity |
| True negative | Good outcome | No alert for non-suspicious activity |
| False negative | Bad outcome | No alert for suspicious activity |
Because they are not constrained by binary rules, AI solutions are able to detect more anomalous behavior and identify more risk patterns, leading to better coverage of real risk. This creates what seems like a paradox: better risk coverage and more detected instances of financial crime, through fewer alerts.
A major hindrance to a traditional rule-based approach is its inability to detect new typologies or threats. Criminals adapt quickly, circumventing standard rules and thresholds by devising new methods for laundering illicit funds. Harnessing technology, nefarious actors innovate to evade detection or outsource to technology-savvy professional criminals, who offer what is essentially money-laundering-as-a-service.
Because rule-based systems are not agile enough to contend with the fast-evolving nature of criminality, firms become vulnerable to bad actors who learn to bypass and outsmart existing controls.
Conversely, AI can learn to identify previously unidentified risk indicators and more nuanced, complex criminal networks, thus offering better protection from illicit activity.
Features of an AI system
- Operates independently of rules and models, analyzing big data to establish a baseline of normal behavior and identify patterns and anomalies.
- Continuously improves and adapts to changing realities, enhancing accuracy through ongoing learning from the data sets.
- Integrates seamlessly without the need for constant rule programming and reprogramming, making onboarding faster, easier and cost-effective.
- Enhances detection accuracy and minimizes false alerts, reducing the resources required for monitoring and management.
- Identifies previously undetected risks by deriving conclusions directly from the data rather than from predefined rules programmed by developers.
- Provides a comprehensive audit trail on alerts for transparent reporting to regulators.
How does data fuel transaction monitoring?
Data is an integral part of effective transaction monitoring. If there are limited data points to enable intelligent, quality alert generation or to properly contextualize a transaction during an investigation, then an institution's transaction monitoring suffers as a result.
Poor data analysis leads to slow processes and redundant investigations. Sophisticated machine learning solutions draw on multiple data points to identify patterns and connections, producing alerts with a deeper level of detection and accuracy.
Network visualization, which involves showcasing different data points in a clean and easily digestible manner, is an essential component of an effective machine learning solution. These data points include risk indicators such as high-risk jurisdictions, flagged counterparties and the historical activities of a client, which help analysts form links to find suspicious connections that are potentially indicative of financial crime.
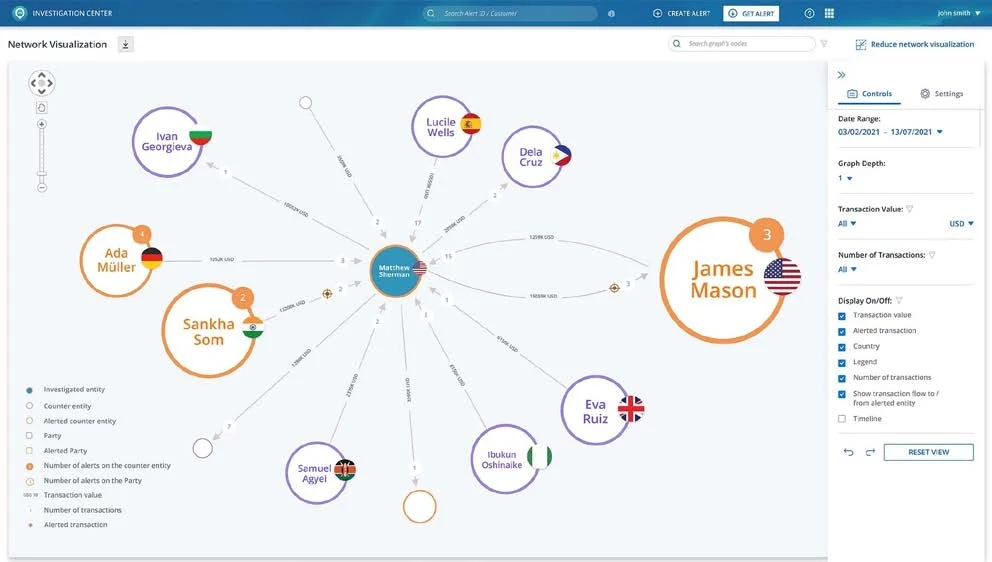
While different financial institutions have different datasets, AI is able to cater to all needs, including working with startups or early-stage firms.
Conversely, for large financial institutions that might have different operating models spanning various countries, AI can help segment localized data to draw out trends in specific subsets. There are also a number of jurisdictional challenges and nuances that AI solutions can help address.
For example, institutions operating in emerging markets may be challenged by a lack of digitized databases or unavailable official data records, such as corporate or property records. Remittance firms often have sparse Know Your Customer (KYC) data and infrequent transactions to draw on, making it difficult to determine the baseline of normality for an individual client. Because AI solutions enhance detection by analyzing trends across datasets, they can provide more accurate results in use cases such as these.
Case study: Travelex Bank
Travelex Bank is Brazil's largest foreign exchange provider, offering a range of international money transfer products including import/export, remittances and mass payments. The bank contends with stringent Brazilian regulation and, as it operates in mass payments, generates huge volumes of transactions every day. Travelex Bank implemented the ThetaRay Transaction Monitoring anti-money laundering solution for both domestic and international transaction monitoring, as well as real-time sanctions screening for its international payments.
3 days
to complete the proof of concept
30,000
transactions processed per minute in the POC
2 months
to full integration
10x
reduction in false positives
- In the proof of concept (POC), completed in only 3 days, Travelex Bank was able to process 30,000 transactions per minute.
- Full integration was completed in only 2 months.
- Travelex Bank reported a 10x reduction in false positives.
- Increased efficiencies from deploying an AI solution allowed for a 30-40% predicted business growth.
How can AI-driven compliance enable business growth?
Deploying an AI-powered solution is often viewed as cost prohibitive, and justifying those costs is front and center of decision-making for businesses. However, AI solutions can help accelerate business growth in a number of ways:
- Enhancing risk detection: Detect real instances of financial crime as well as previously unidentified typologies, increasing risk coverage. AI also enables analysts to focus on value-add activities: identifying opportunities for business growth, highlighting trends, supporting wider stakeholders with reporting and drawing more impactful insights from data.
- Enabling business scalability while controlling compliance cost: Allow firms to process more transactions without proportionally increasing compliance costs, enabling business expansion and increased client acquisition.
- Expanding business scope: AI-powered transaction monitoring is better at detecting real risk and handling business fluctuations, so firms can expand their scope of business confidently without necessarily increasing their risk exposure. An institution can thus explore new clients or deals in jurisdictions previously deemed too risky.
- Encouraging financial inclusion: Provides the ability to serve the traditionally underbanked and encourage financial inclusion.
- Reducing false positives: Reduce the need for large teams of analysts investigating unproductive alerts. Eliminating unnecessary investigation work provides long-term benefits, including staff retention. With 87% of organizations having no additional capacity due to staffing issues, it is crucial that firms focus their teams on value-added contributions.
- Ensuring regulatory compliance: Global AML penalties are on the rise, with fines surging more than 50% in 2022. A robust AML compliance program helps avoid severe fines.
- Evolving FCC detection: No need for constant reconfiguration, with the ability to continuously learn and adapt based on ongoing data collection and analysis.
Case study: NOW Money
NOW Money is a Dubai fintech and the Gulf Cooperation Council's first mobile banking solution focused on financial inclusion. It helps customers excluded from the traditional banking system send remittance payments abroad as quickly and cheaply as possible. NOW Money partnered with ThetaRay to monitor cross-border payments and support the detection of financial crime.
“Anything to do with cross-border requires the best technologies and the ability to use AI. From NOW Money's perspective, we want to be best-in-breed when it comes to compliance, audit and governance, so we need to work with good parties like ThetaRay.”
Noel Connolly, CEO, NOW Money
Adopting an AI monitoring solution has helped NOW Money process transactions efficiently so that its customers' families can receive payment without delay. The number of false positives has dropped dramatically, and the centralized investigation dashboard allows for the quick distribution of work so cases are dealt with faster. The solution also instantly screens beneficiaries, which enables teams to deal with flagged individuals and alerts immediately, speeding up the process and retaining customers by preventing unnecessary customer friction.
Simpler integration and ongoing use
Most obviously, financial institutions that leverage AI solutions in their FCC programs benefit from enhanced risk detection, which helps them remain compliant with regulations and avoid hefty fines.
Another important benefit is the simple integration and ongoing use of AI solutions. Traditional rule-based solutions require regular testing and reprogramming of scenarios and thresholds. Upon discovering a new financial crime typology, it can take 6-12 months to reprogram legacy systems to detect it.
By then, criminals have likely devised new methods, rendering the solution out of date again. Conversely, AI solutions do not need constant reconfiguration and are able to continuously learn and adapt based on ongoing data ingestion and analysis.
Conclusion: transforming compliance from cost to profit with AI
As criminals innovate and crimes become more complex, financial institutions must adapt. Rule-based systems are resource-intensive, provide only partial coverage, generate increased false positives and unintentionally introduce bias. Their inefficiencies strain compliance resources and leave firms vulnerable to bad actors and regulatory fines.
By adopting a risk-based approach with AI, firms can enhance transaction monitoring, identify previously undetected risk, increase overall risk coverage, reduce compliance costs and ensure regulatory compliance. AI-powered solutions transform compliance from a cost center to a profit generator, allowing financial institutions to expand into new markets and customer segments previously deemed too risky, all while maintaining compliance.
About FINTRAIL
FINTRAIL is a global financial crime consultancy. FINTRAIL has worked with over 100 leading global banks, fintechs, other regulated financial institutions, RegTechs, venture capital firms and governments to implement industry-leading approaches to combating money laundering and other financial crimes.
With significant hands-on experience, FINTRAIL helps firms build, strengthen and assure their transaction monitoring programs to meet evolving regulatory requirements, use technology effectively and stay competitive.
Sources
- FATF, Risk-Based Approach for the Banking Sector
- Global Investigation Review, 2020
- ThetaRay research, 2023
- Europol
- Deloitte, 2023
- Financial Times, 2022
Frequently asked questions
What is the difference between rule-based and risk-based transaction monitoring?
Rule-based transaction monitoring relies on static, one-size-fits-all rules and thresholds tied to predefined typologies. A risk-based approach uses adaptive systems, such as AI, that establish a baseline of normal behavior from the data and target genuine threats rather than check-box compliance.
Why do rule-based AML systems generate so many false positives?
Rule-based AML systems are constrained by binary rules, so they flag large volumes of unsuspicious activity while missing behavior that does not match a predefined typology. Industry research estimates a 95% false positive rate for rule-based transaction monitoring.
How much can AI reduce false positives in transaction monitoring?
AI transaction monitoring solutions can reduce false positives by up to 95%, creating a smaller volume of alerts for analysts to investigate. In one example, Travelex Bank reported a 10x reduction in false positives after implementing ThetaRay.
How long does it take to update a legacy AML system for a new typology?
Upon discovering a new financial crime typology, it can take 6-12 months to reprogram legacy rule-based systems to detect it. AI solutions do not need constant reconfiguration because they continuously learn and adapt from ongoing data ingestion and analysis.
Can AI transaction monitoring work with sparse KYC data?
Yes. Remittance firms and institutions in emerging markets often have sparse KYC data, infrequent transactions or limited official records. Because AI solutions enhance detection by analyzing trends across datasets, they can provide more accurate results in these use cases.
How does AI-driven compliance support business growth?
AI-driven compliance lets firms process more transactions without proportionally increasing compliance costs, expand into jurisdictions previously deemed too risky and serve the traditionally underbanked. Travelex Bank's efficiency gains from AI allowed for a 30-40% predicted business growth.